Sheet A-4 · Guide
Planning a bigger suite on a flood-zone lot? Price it against the house first
You have a plan for a suite on the ground floor, and your street floods in a bad storm. Before you pick a size, find out whether the cost will reach half the value of your house. If it does, the whole house, not only the new room, must meet current flood rules. Most places use half (50 percent), and a few use 49 percent. Send your address and we will find your numbers.
- Counties
- Hillsborough, Pinellas, Pasco
- Phone
- (315) 640-3590
- Offer
- $100 off your first job
Why a flood-zone addition has a price ceiling
A suite looks like a simple job: a bedroom, a bath and a door. On a flood-zone lot, the building office also asks how the cost compares with the value of your house. That comparison comes from federal flood insurance rules, and the building offices around Tampa Bay apply it.
The rule does not ban additions. It changes what you must build once the cost crosses a line, so you want to know where the line sits before anyone draws. Ask your building office for the number and bring it to your first contractor meeting.
Three rules
The three rules, in one place

Kitchen or no kitchen
Will the suite have its own kitchen?
A suite with its own kitchen is a second dwelling. Your city or county decides if it fits your lot.

Flood zone, half value
Is your home in a flood zone?
In a flood zone, half your home's value is the trigger. Past it, the whole house meets current flood rules. Most places use half (50 percent). Unincorporated Pinellas, St. Petersburg, Safety Harbor and unincorporated Pasco use 49 percent.
You are reading this one

Parent aged 62 plus
Will a parent or grandparent live there?
New space is assessed on top of your capped value. A county reduction may apply. The parent must be 62 or older.
Basis: Florida Statutes section 163.31771, Hillsborough County Land Development Code
How the test measures your addition
Federal rules label an addition or other improvement a substantial improvement when it costs half the building's market value or more. Market value is measured before construction starts.
FEMA's desk reference adds that such an addition must meet flood rules itself. If it is structurally tied to the house, the existing building must meet them too. Ask a contractor whether your suite could stand as a separate structure, and what that does to the price and the layout.
Where the line is 49 percent
Unincorporated Pinellas County uses a 49 percent structure-value line, and the county says it covers all improvements, not only storm repairs. The City of St. Petersburg says remodeling in the flood zone is limited to 49 percent of the home's value.
Safety Harbor's flood code counts an improvement that reaches 49 percent of the structure's market value. Pasco County's local amendment to the Florida Building Code sets 49 percent too, and the page does not say it covers the cities, so treat it as the rule for unincorporated Pasco.
Most places use half (50 percent). If your lot is in unincorporated Pinellas, St. Petersburg, Safety Harbor or unincorporated Pasco, treat 49 percent as your ceiling. If you live in another city, ask that city's building office which line it uses, and write the answer down.
Where the value of your house comes from
The test needs a number for the house, and each office finds it differently. The Pinellas County Property Appraiser publishes a letter for each parcel that shows the structure value used in the test. Tampa prices the work with a square-foot cost table and sets it against the appraiser's value of the existing structure.
New Port Richey takes the appraiser's assessed structure value or a state-licensed appraisal, and asks for a cost estimate signed by the contractor, with an affidavit that it covers all improvements. Ask your own office for its form before you collect any price.
What counts on the cost side
Unincorporated Hillsborough County counts owner or volunteer labor and donated materials at market value. Doing part of the work yourself therefore does not shrink the figure. Ask the contractor to price every part of the job, so the number on paper matches what the office will count.
Side addition, second story or remodel
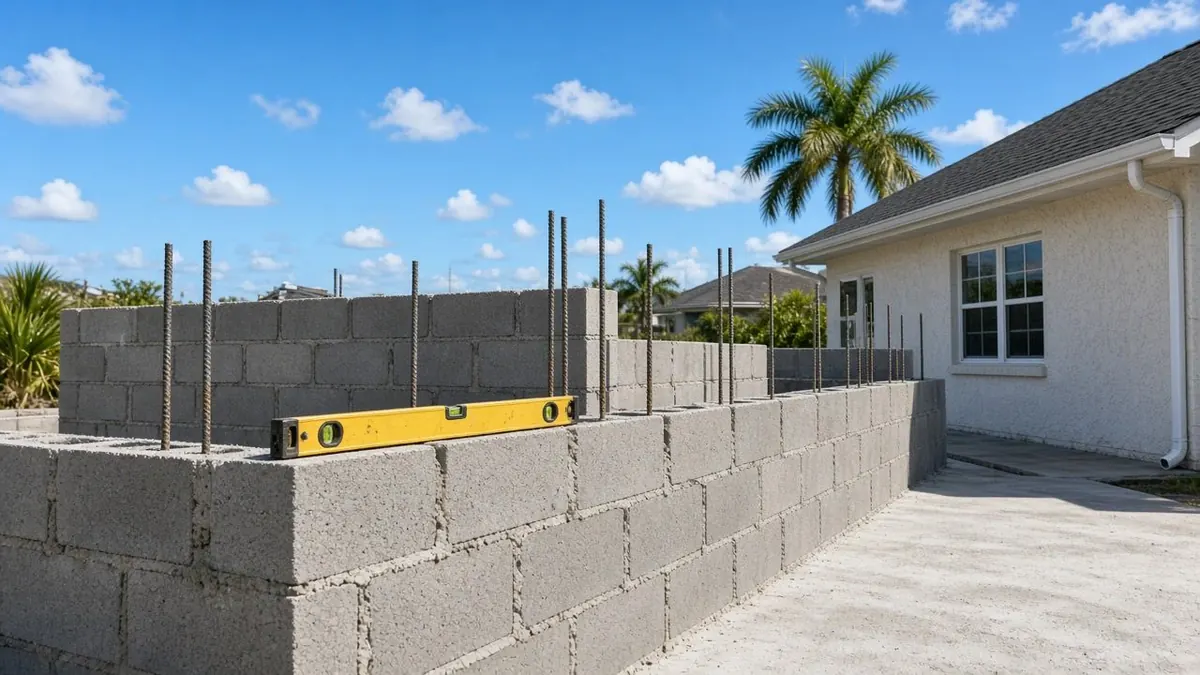
Plan for the suite you want, then ask for a second, smaller plan priced as its own full written scope, and compare each total with the line. A side addition that passes the line must meet flood rules, and attaching it to the old house can bring the old part into the same rules. With two plans in hand, you can compare the price of each and choose with the facts on the table.
What may sit below the flood line
In New Port Richey, only parking, a way into the building and a little storage may sit under the base flood elevation. Bathrooms, laundry rooms and mechanical equipment must go at or above it. That matters for a ground-floor suite on a low lot, and for a garage that you hope to turn into a bath and bedroom.
Ask your building office for the base flood elevation at your address. Then ask the contractor to mark the finished floor height on the plan, measured from the door.
Planning a smaller suite on purpose
A smaller suite is not a lesser one. A bedroom, a bath, a closet and a place to sit can fit in a modest footprint if the layout is tight. Ask the contractor to draw the plan twice: once with every room you want, and once with the rooms you need.
Compare each against the line your office uses. If the smaller plan clears it, you may save money and keep the rest of the house out of the new rules. Send us both plans and we will ask the right questions.
What going over the line can mean for your plan
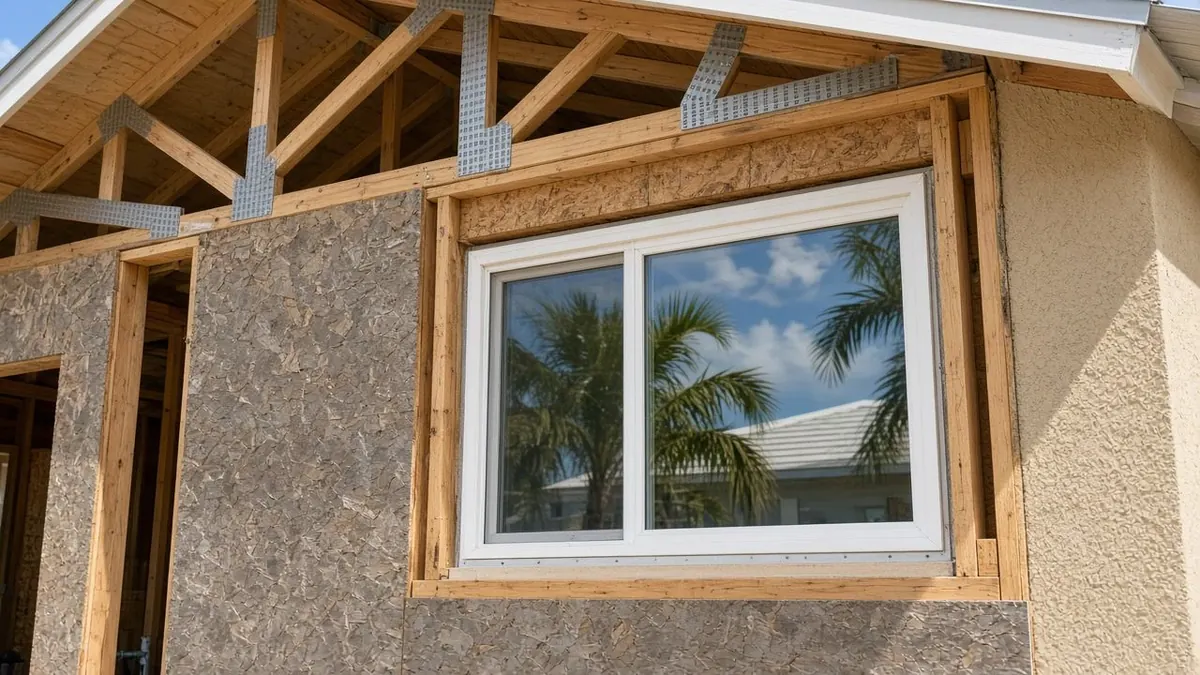
When an addition crosses the line, the whole house may need to meet current flood requirements, and those can include raising the lowest floor. That changes the price, the layout and sometimes the lot plan, because a raised floor needs steps or a ramp at the door.
Ask your contractor to price the over-the-line plan next to the under-the-line plan. The gap between the two numbers tells you what the extra square feet really cost, and you can decide with both in front of you.
Two plans, side by side
Families planning for a parent often want the biggest suite the lot allows. Start with the version your parent needs: a bedroom, a bath and a place to sit. Then ask what it would take to grow the plan by a closet, a laundry or a porch.
Each extra room moves the cost closer to the line. If your lot is in a flood zone, ask the contractor to price each room as its own line and show the total. You will see where the line falls, and you can stop there or go past it with open eyes.
If your home was damaged in the 2024 storms
After Hurricanes Helene and Milton, Tampa began mailing Substantial Damage Assessment Letters on December 9, 2024. A home found substantially damaged cannot be repaired without meeting current floodplain and building code.
If you received a letter, or think you should have, call the building office before you plan an addition. Ask how the letter bears on any new work, and send us what the office says.
How to ask your building office, step by step
- Have your parcel number or street address ready.
- Ask whether the parcel is in a flood zone.
- Ask which structure value the office uses and where you can see it.
- Ask how it measures the cost of the work.
- Ask for the answers in an email or a letter.
Keep the reply with your plans, and give a copy to every contractor you meet. Send us the address and we will find the office and the numbers for you.
When the half-value rule is not your question
If your lot is outside a flood zone, this test may not be the main issue. Your lot limits and your budget will matter more. Confirm your flood zone first, then pick the guide that fits your next question.
Flood insurance policies can also include a coverage that pays up to $30,000 toward elevating or floodproofing a building after a flood has substantially damaged it. That is a question for your insurance agent, and it is not a reason to build. Call us when you are ready to check your numbers.
We find out what your lot allows, then put you in touch with a contractor near you, who does the building.
Tell us about the space
Send the address and what you have in mind. The rules for that lot come first.
- Your request is in Keep your phone close. A call comes from (315) 640-3590.
- The lot comes first We look at what your city or county allows at that address.
- Then a contractor You meet a local contractor and see the price in writing.
$100 off your first job We credit $100 on the first job you book with our help.
- We pay the $100, so the contractor's price stays as quoted.
- One credit per customer for each home.
- Your job must be booked by December 31, 2026.
- Say you want the credit when you book.
The Senior Home Additions promise
- 1 Your first call and your request are free.
- 2 Planning with us costs you nothing.
- 3 We check the rules at your address before anyone quotes.
The Senior Home Additions promise
- 1 Your first call and your request are free.
- 2 Planning with us costs you nothing.
- 3 We check the rules at your address before anyone quotes.
- 4 We credit the $100 the way our Terms describe.
Your agreement with the contractor you hire covers the building.
Senior Home Additions, (315) 640-3590 Read the full terms
$100 off your first job We credit $100 on the first job you book with our help.
- We pay the $100, so the contractor's price stays as quoted.
- One credit per customer for each home.
- Your job must be booked by December 31, 2026.
- Say you want the credit when you book.
Send your address and ask where your flood line sits.